Insurance brokerages
Insurance agency marketing for California's new insurance market
Bound policies and fuller households for California agencies, with honest guidance for homeowners and licence numbers on everything.
Trusted by 50+ D2C brands · Google, Meta & Shopify partners
Non-renewed homeowners are searching for help
San Francisco, CA
Agencies statewide
Licence on everything
Insurance Code §1725.5
Bound policies
Not quotes
A homeowner in Altadena who just received a non-renewal letter doesn't search for 'cheap home insurance'. They search 'can't find homeowners insurance', 'FAIR Plan alternatives' or 'insurance broker near me who can help'. The California FAIR Plan was reported at about 696,500 policies in June 2026. Insurers are starting to return under the state's Sustainable Insurance Strategy, but it's slow, and people need an agent who understands the market.
For independent agencies, that's an opportunity and a responsibility. Clients want honest guidance about the FAIR Plan, surplus-lines options, difference-in-conditions policies and which carriers are writing again. Marketing that promises 'big savings' to someone who's just lost coverage destroys trust; content that explains their options earns it, and the auto, umbrella and commercial business that follows.
We work with agencies as part of financial services marketing in California, and our California agency in San Francisco. Every ad, quote, business card and email carries your California licence number, as Insurance Code §1725.5 requires, and we report on bound policies.
Three changes every agency is dealing with
Each one changes what clients need from your marketing.
Homeowners need help, not offers
Non-renewals pushed hundreds of thousands of households onto the FAIR Plan. These clients need someone to explain their options, including FAIR Plan plus a DIC policy, surplus lines or carriers returning under the Sustainable Insurance Strategy. 'Save 20%' advertising doesn't match their situation. Clear, current guidance does.
Licence numbers must appear everywhere
Insurance Code §1725.5 requires your California licence number on business cards, written quotations and print ads, at least as large as any phone number shown, and since 2023 on email too. A National Producer Number doesn't count. Agencies often miss it on social posts, landing pages and email templates.
One policy is rarely enough
Agencies grow on households and businesses with several policies, but many market one line at a time. A client who comes in for home insurance often needs auto, umbrella or business coverage. Without a cross-sell plan, that business goes elsewhere.
Six pieces of work, home to commercial
Crisis-ready content and search
Clear, regularly updated pages on non-renewals, the FAIR Plan, DIC policies and returning carriers, ranking for the questions homeowners actually ask.
Local SEO and reviews
Google Business Profiles, office pages and review programmes for every location. Insurance is still a local, trust-based purchase.
Licence-compliant templates
California licence numbers built into every ad, landing page, quote template and email signature, sized as the law requires.
Referral programmes
Partnerships with real estate agents, mortgage lenders and contractors, whose clients need insurance at key moments.
Cross-sell and retention
Email and SMS campaigns that offer auto, umbrella and business coverage to existing clients, plus renewal reminders.
Commercial-lines lead generation
Search and LinkedIn campaigns for small and mid-size businesses by industry, from restaurants to contractors.
Five insurance markets, five risk profiles
Where coverage is hardest to find, and what agencies need to explain.
Los Angeles
The January 2025 fires hit Altadena, the Palisades and Malibu, and many foothill and canyon homeowners face non-renewals. Clear guidance and rebuild-coverage expertise matter most.
Bay Area hills
Oakland and Berkeley hills, Marin and the Santa Cruz Mountains have high fire risk and high home values. Coverage above the FAIR Plan's $3 million cap is a frequent need.
Sierra foothills & Lake Tahoe
Some of the hardest-to-insure homes in the state. Agents who can place coverage are in high demand, and referral relationships with lenders and agents are vital.
Orange County & San Diego
Coastal and canyon homes with high values, plus large auto and commercial markets. Bundling home, auto and umbrella drives agency growth.
Inland Empire & Central Valley
Growing family neighbourhoods, many small businesses and price-sensitive auto buyers. Spanish-language service and commercial lines matter.
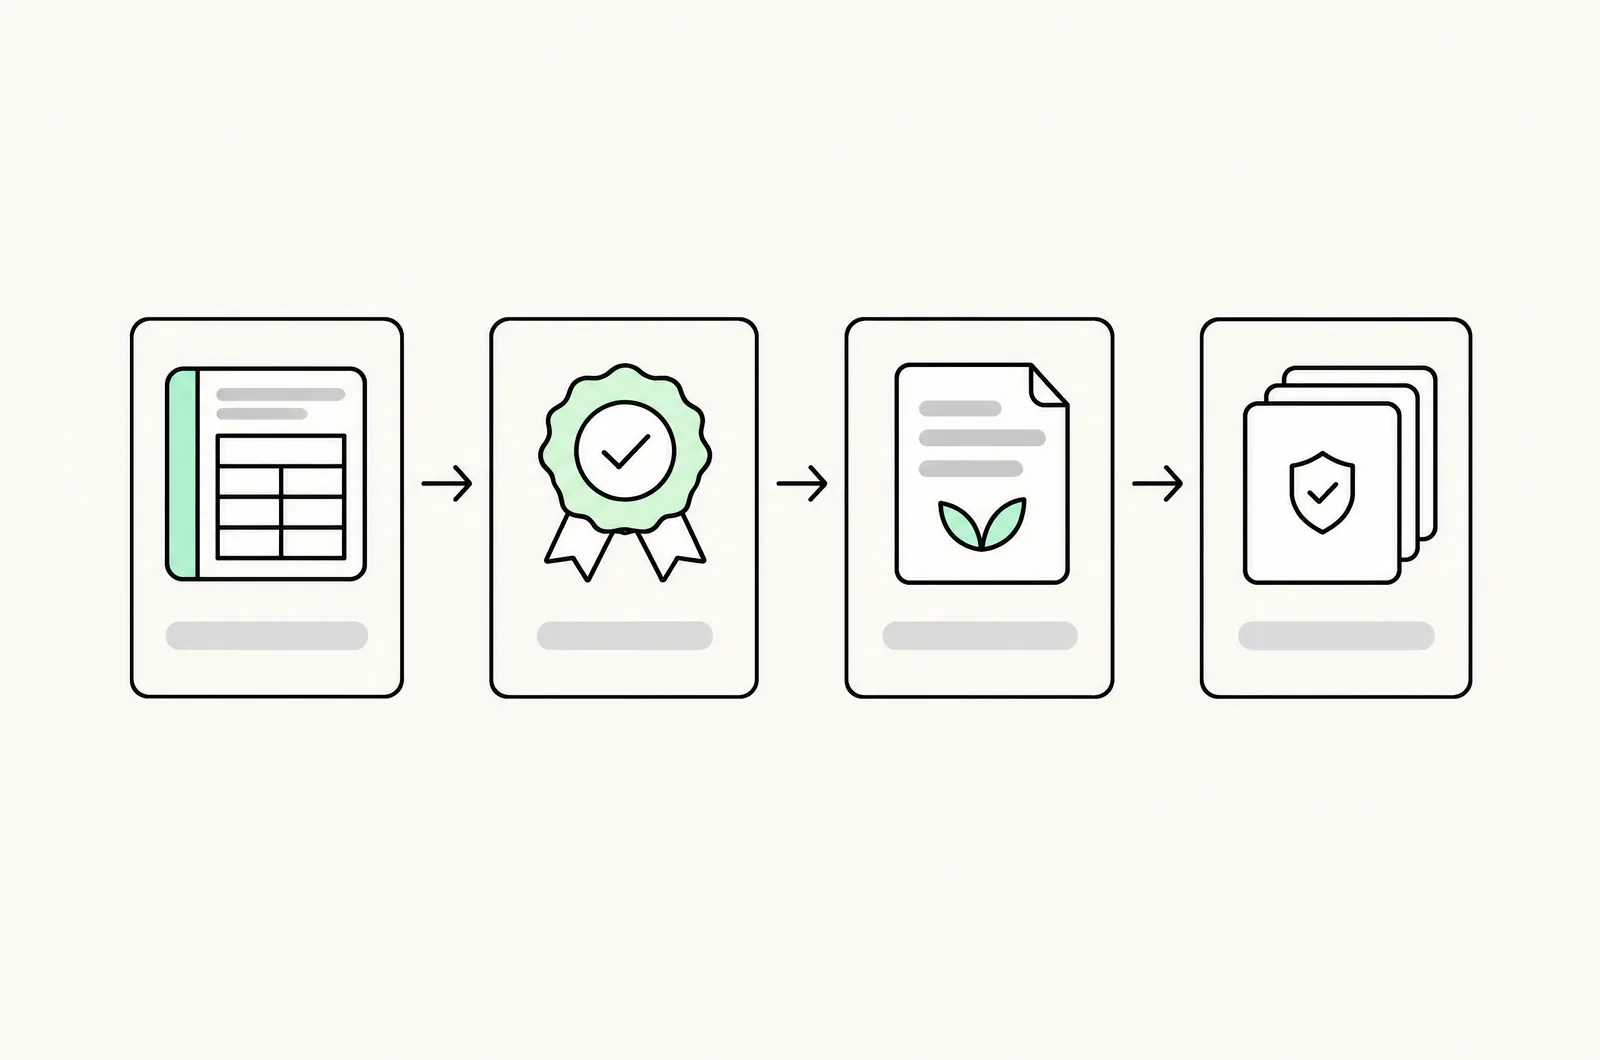
From book audit to bound policies
- Step 01
Book and source audit
Policies by line, client, region and source, plus retention and cross-sell rates.
- Step 02
Compliance templates
California licence numbers and claims rules built into every ad, page, quote and email template.
- Step 03
Content, search and referrals
Crisis-ready content, local SEO, referral programmes and commercial-lines campaigns.
- Step 04
Report bound policies
Monthly quotes, bound policies, policies per client and retention by source.
An agency-marketing specialist vs a lead vendor vs an in-house marketer
In-house costs are directional and depend on seniority and metro.
Licence number on ads, quotes and email
- Lead vendor
- Often missed
- In-house California hire
- Depends
- Conversion (San Francisco)
- Yes
Current FAIR Plan and non-renewal content
- Lead vendor
- Generic savings ads
- In-house California hire
- If time allows
- Conversion (San Francisco)
- Yes
Referral programmes with agents and lenders
- Lead vendor
- No
- In-house California hire
- Producers' own
- Conversion (San Francisco)
- Yes
Cross-sell and retention campaigns
- Lead vendor
- Separate vendor
- In-house California hire
- Manual
- Conversion (San Francisco)
- Yes
Reports bound policies by source
- Lead vendor
- Quote requests
- In-house California hire
- AMS reports
- Conversion (San Francisco)
- Yes
Typical monthly cost
- Lead vendor
- $1,500–$6,000 lead package
- In-house California hire
- $8,000+ per marketer (directional)
- Conversion (San Francisco)
- From $4,000 fee
Brand search, stated plainly
- Local brand search · national
95%
Brand impression share
NP Digital: owning your own name
NP Digital isn't an insurance agency or a California client, and we have no published insurance result. What carries over is brand-search discipline: holding 95% of impression share on your own name, so prospects who ask a friend about you find you, not a comparison site.
What insurance marketing costs in California
USD, excluding media. Commission-share terms are structured to comply with California rules.
Agency foundation
From $4,000/mo
One or two offices
Licence-compliant templates, crisis-ready content, local SEO and reviews, and bound-policy reporting. Media is separate.
- Licence-number templates
- FAIR Plan content
- Bound-policy report
- Most popular
Agency growth
$7,500–$14,000/mo
Multi-office · personal + commercial
Everything in the foundation, plus referral programmes, cross-sell and retention, and commercial-lines campaigns.
- Referral partnerships
- Cross-sell campaigns
- Commercial lines
Pay-on-results
Base + share
Qualifying agencies
A lower base plus a share of first-year commission on attributed new policies above an agreed baseline, structured to comply with California rules on sharing commission.
- Baseline agreed up front
- Compliance-reviewed structure
- Same reporting
Insurance agency marketing questions
Do California insurance agents need their licence number on marketing?
How should agencies market to homeowners who were non-renewed?
What is the Sustainable Insurance Strategy?
How do agencies get referrals from real estate agents and lenders?
Which California insurance markets do you work in?
How much does insurance agency marketing cost?
Should agencies buy shared insurance leads?
How do you measure insurance marketing?
Related California pages
Financial services marketing in California
The parent practice for lenders, advisers and insurance agencies.ExploreMortgage & lending marketing
A sibling, and a key referral partner for home insurance.ExploreWealth management marketing
A sibling: advisers under the SEC Marketing Rule.ExploreLuxury real estate marketing
High-value listings where insurability decides the sale.Explore
Sources and statutes
Every figure and regulation cited on this page.
Facts and thresholds last checked 19 November 2026.
- California Insurance Code §1725.5 — license number on business cards, quotes and print adsLicensees must print their California license number on business cards, written price quotations and print ads; since 2023 also on email (SB 1242).
- Insurance Journal — California FAIR Plan policy growth slows (September 2026)Reported at about 696,500 FAIR Plan policies in force in June 2026, with quarterly additions falling for five quarters.
- California Department of Insurance — Natural catastrophe and insurance overview, August 2026 legislative briefTwelve insurance groups have filed under the Sustainable Insurance Strategy; catastrophe models and reinsurance costs now allowed in rate filings.
- California FAIR Plan Association — residential dwelling coverageResidential limit of $3 million combined for dwelling, other structures and contents.
Help the homeowners who are searching now
30 minutes with a senior strategist. Bring your book mix and lead sources if you have them.
What happens next
- 1Pick a time for a 30-minute call.
- 2We review content, templates and referral sources.
- 3Get a plan measured on bound policies.
Prefer email? tarun@conversion.is