Financial services \u00b7 California
A financial services marketing agency that knows the California rules
Funded loans, new assets and bound policies for California lenders, advisers and insurance agencies, with licence disclosures on every ad.
Trusted by 50+ D2C brands · Google, Meta & Shopify partners
A market that moved in two years
San Francisco, CA
Statewide coverage
Disclosure-ready
NMLS · CDI · SEC
Funded and bound
Not leads
California's home-insurance market shows how far a financial category can move in two years. The state's insurer of last resort, the FAIR Plan, was reported at about 696,500 policies in June 2026, and the Department of Insurance says twelve insurer groups have now filed to expand under its Sustainable Insurance Strategy. For brokers, lenders and advisers, that one market now shapes mortgage closings, home-buying decisions and client conversations.
Financial marketing in California is also one of the most rule-bound jobs in advertising. Mortgage loan originators must show their NMLS identifier on every ad that solicits borrowers. Insurance licensees must print their California licence number on print ads, quotes, business cards and, since 2023, email. Advisers follow the SEC Marketing Rule or state rules on testimonials. CCPA governs every lead form. Each rule changes what a campaign can say.
We run financial services as one of nine verticals in our California practice, from San Francisco. The work is client acquisition built for regulated offers: search and SEO for high-intent questions, paid social with the right disclosures, lead nurture for long decisions, and reporting tied to funded loans, new assets under management and bound policies.
This page covers financial services broadly: lenders, wealth managers, insurance agencies and consumer fintechs. Mortgage and lending, wealth management and insurance brokerages each have their own page, because the regulator, the buyer and the sales cycle differ.
Why financial marketing is harder in California
Each problem comes from licensing rules, data sensitivity or the cost of reaching high-value clients.
Every ad carries a licence obligation
NMLS identifiers on mortgage solicitations (B&P Code §10235.5), California licence numbers on insurance ads, quotes and email (Insurance Code §1725.5), and testimonial disclosures for advisers. Miss one and the ad is a regulatory problem, not just a weak ad. Generic agency templates rarely carry any of them.
Lead forms collect the most sensitive data
Income, assets, credit and property details make financial lead forms high-risk under the CCPA, and the federal Gramm-Leach-Bliley Act covers much of what happens after. Pixels on application pages and long forms that ask for too much create privacy exposure and lower conversion at the same time.
High costs meet high-value clients
Financial-services clicks in California are among the most expensive anywhere, because one client can be worth years of fees or a large loan. Paying for volume rarely works. You need campaigns aimed at the questions serious prospects ask, and measurement that rewards the channels producing funded, invested or bound business.
Eight workstreams, one closed-business report
Licence-compliant ad templates
NMLS IDs, California insurance licence numbers and required disclosures built into every ad, landing page and email template, so a missed number can't ship.
High-intent search and SEO
Campaigns and content on the questions serious prospects ask, from 'jumbo loan Bay Area' to 'fiduciary adviser Los Angeles'. Broad financial terms burn budget on researchers and students.
Paid social with financial disclosures
Meta and LinkedIn campaigns within Google and Meta's financial-services and credit policies, with no prohibited targeting for credit offers and the right disclosures on every claim.
Privacy-safe lead forms
Short forms that collect only what's needed to make contact, CCPA notices and opt-outs, and no ad pixels on application or account pages.
Long-cycle nurture
Email education and follow-up for decisions that take months, such as refinancing, retirement planning or switching insurers, with consent and opt-outs handled properly.
Reviews and reputation
Review programmes on Google and industry sites, within SEC or state rules for advisers and with licence numbers where insurance rules require them.
Spanish-language and multilingual campaigns
Spanish, Chinese, Vietnamese and Korean pages and ads where your clients need them, with disclosures translated properly too.
Funded, invested and bound reporting
Reporting from lead to funded loan, new assets or bound policy by source, from your CRM or loan origination system.
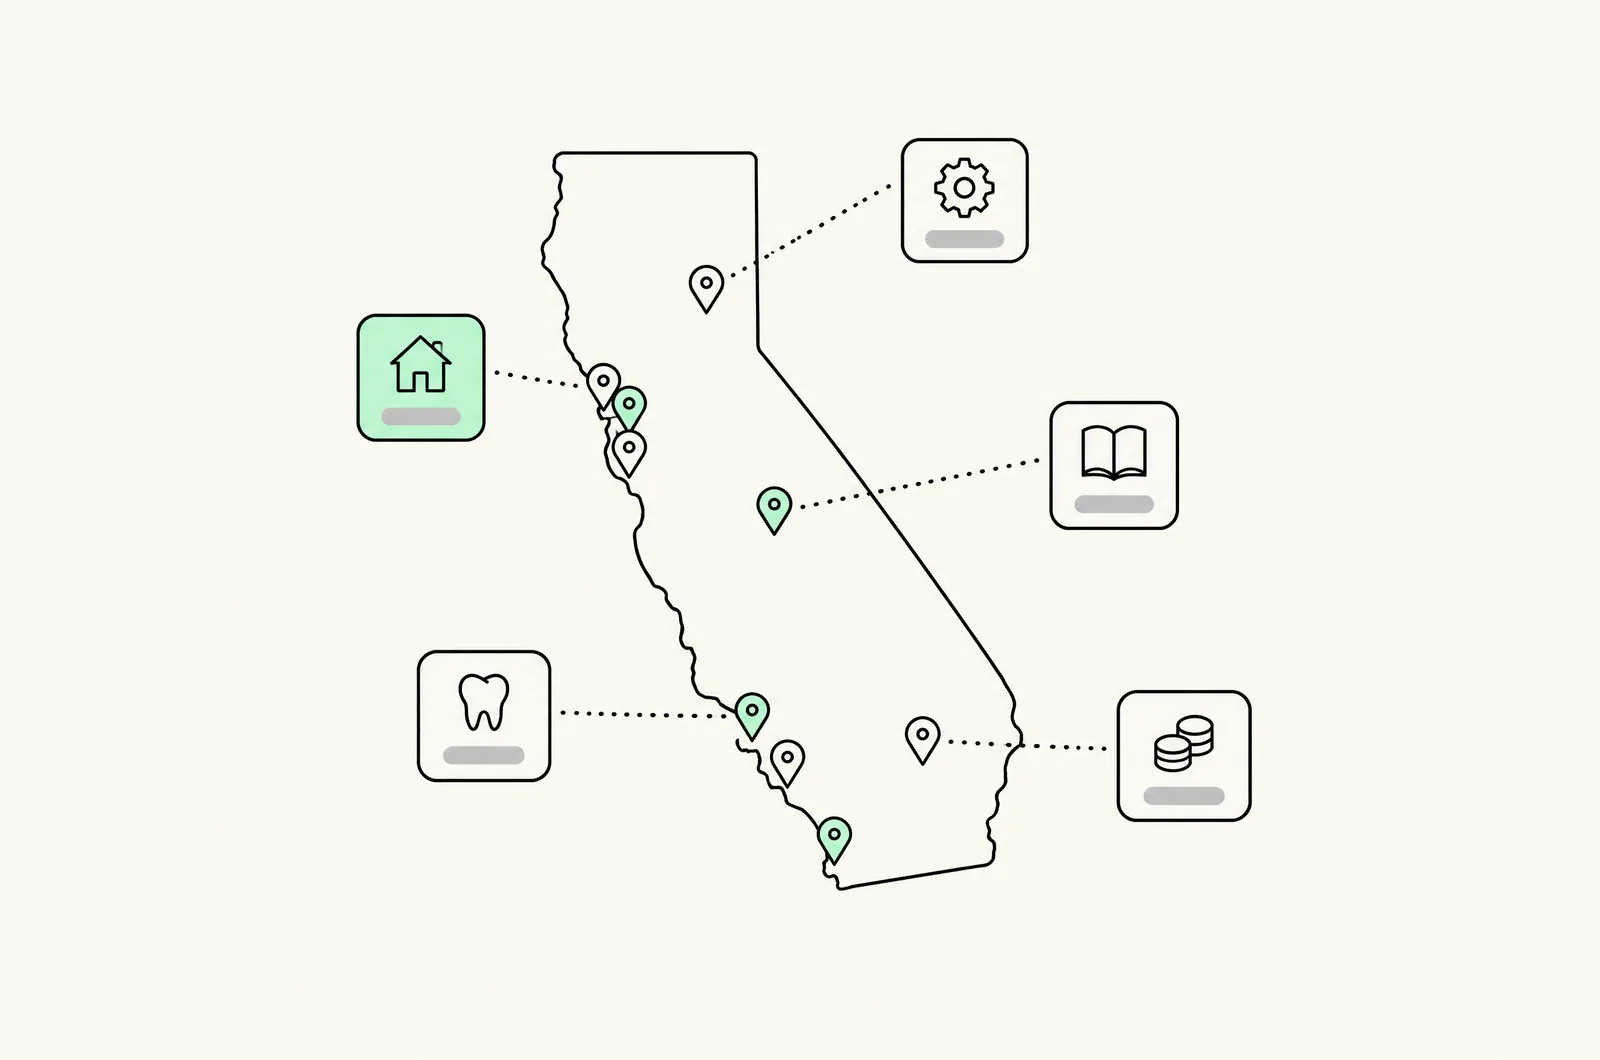
Seven financial markets, seven kinds of client
Who the clients are in each market, and what they need help with.
San Francisco
Tech wealth, equity compensation and some of the highest home prices in the country. Clients need help with RSUs, IPO liquidity and jumbo mortgages.
Silicon Valley & the Peninsula
Founders and executives with concentrated stock, who need tax, estate and lending advice together. Referrals from CPAs and attorneys matter.
Los Angeles
Entertainment and business-owner wealth, a huge first-time buyer market and wildfire-driven insurance changes. Clients are diverse and often multilingual.
Orange County
Retirees, business owners and a large mortgage and insurance industry. Advisers compete hard for retirement rollovers.
San Diego
Military families using VA loans and defence and biotech professionals with equity compensation. VA-lending and relocation content performs well.
Sacramento
State and public employees with CalPERS and CalSTRS pensions, and Bay Area movers buying homes. Pension and retirement planning content draws prospects.
Inland Empire & Central Valley
First-time buyers, price-sensitive borrowers and small businesses. Plain language, bilingual service and FHA lending content win clients.
From compliance audit to closed business
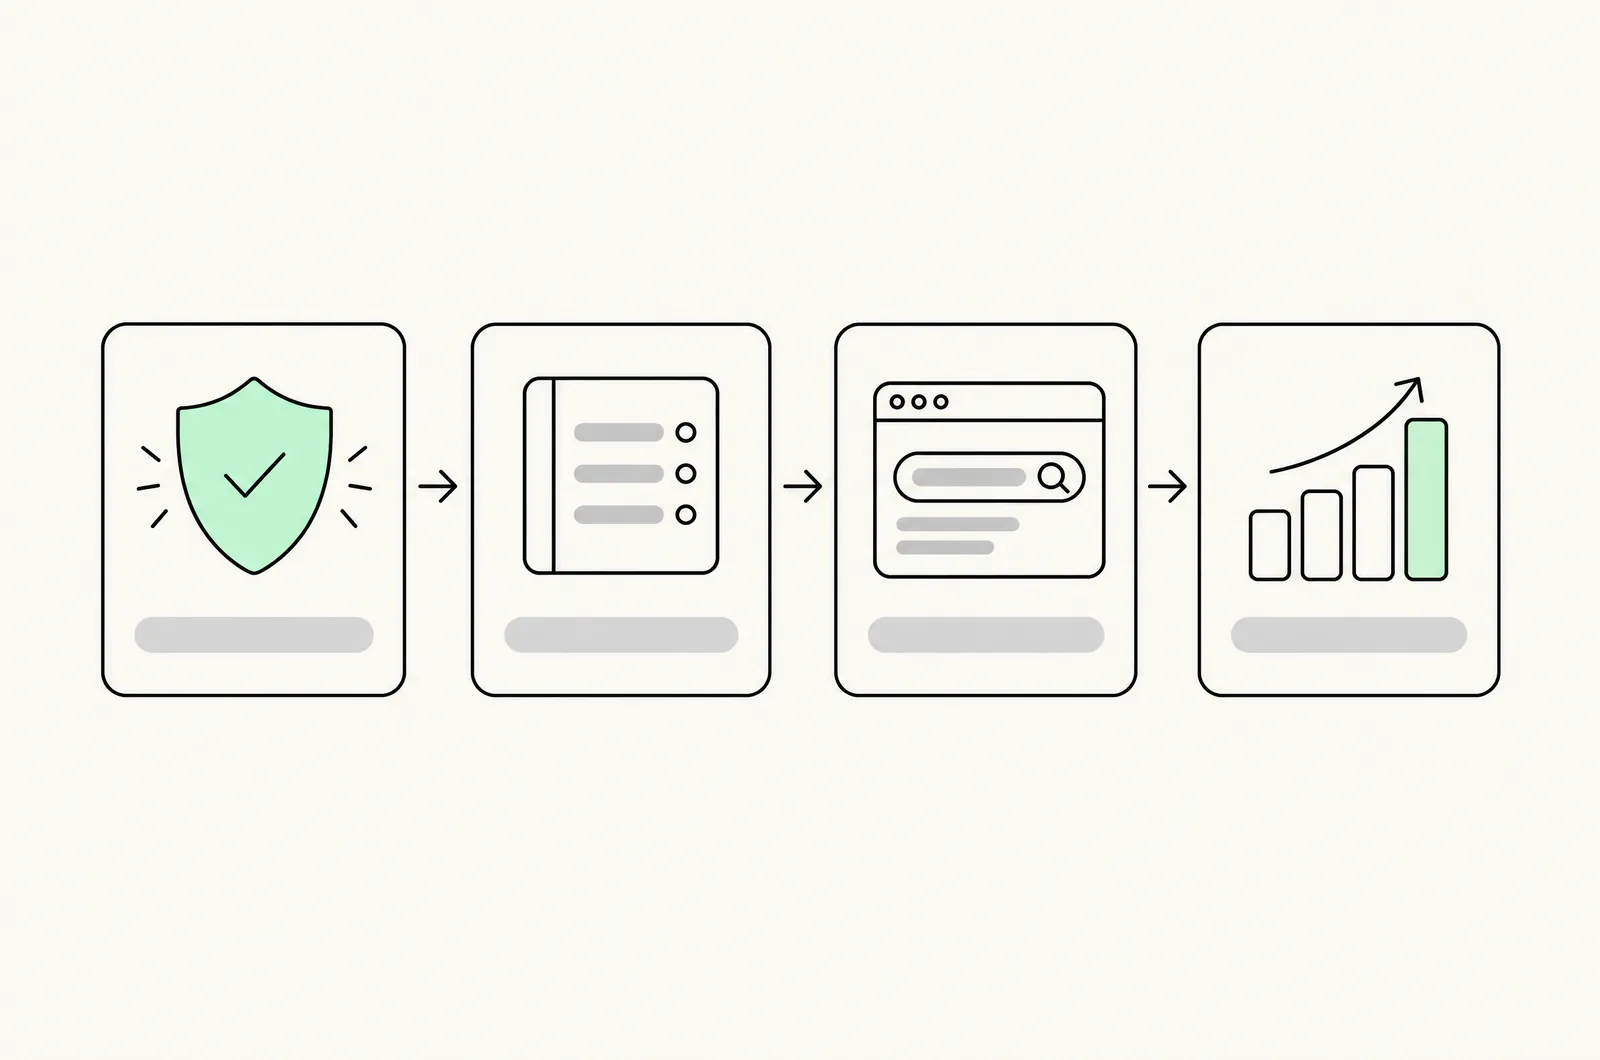
- Step 01
Compliance and tracking audit
Licence disclosures, testimonials, lead forms and tags checked against California and federal rules, with your compliance team.
- Step 02
Client-value baseline
Leads, applications, funded loans, new assets or bound policies by source for the last 12 months.
- Step 03
Build compliant acquisition
High-intent search and SEO, paid social, privacy-safe forms and nurture, with disclosures in every template.
- Step 04
Report on closed business
Monthly funded, invested and bound business by source. Budget moves to what closes.
A California financial agency, an out-of-state agency or an in-house marketer
In-house costs are directional and depend on seniority and metro.
NMLS and CDI licence numbers in every template
- Out-of-state agency
- Often missed
- In-house California hire
- Depends on the hire
- Conversion (San Francisco)
- Yes
SEC or state testimonial rules for advisers
- Out-of-state agency
- Rarely checked
- In-house California hire
- Varies
- Conversion (San Francisco)
- Yes
Privacy-safe financial lead forms
- Out-of-state agency
- Long forms with pixels
- In-house California hire
- Varies
- Conversion (San Francisco)
- Yes
Reports funded, invested or bound business
- Out-of-state agency
- Cost per lead
- In-house California hire
- Spreadsheet
- Conversion (San Francisco)
- Yes
Works with your compliance team
- Out-of-state agency
- Ad hoc
- In-house California hire
- Usually
- Conversion (San Francisco)
- Yes
Typical monthly cost
- Out-of-state agency
- $3,000–$15,000 fee
- In-house California hire
- $11,000+ fully loaded (directional)
- Conversion (San Francisco)
- From $5,000 fee
Regulated fintech, honestly labelled
- Fintech · Canada
4x
App user base
NDAX: regulated fintech acquisition
NDAX is a Canadian crypto exchange, not a California client, so it isn't evidence of California results. It is real financial-services work: Apple Search Ads, Meta and Reddit run as one plan in a regulated category, with monthly optimisation, which grew the app's user base 4x.
Where financial services splits into different businesses
Each line has its own regulator, buyer and sales cycle, so each gets its own plan.
- Live
Mortgage & lending
Lenders and brokers in an $899,720 median market: NMLS disclosures, rate-sensitive demand and purchase versus refinance cycles.
- Live
Wealth management
RIAs and advisers in San Francisco and LA: equity compensation, retirement rollovers and the SEC Marketing Rule.
- Live
Insurance brokerages
Agencies working through the homeowners-insurance crisis: FAIR Plan clients, licence numbers on every ad, and trust.
What financial services marketing costs in California
USD, excluding media. Performance terms are structured to meet each line's compensation rules.
Compliant foundation
From $5,000/mo
One line of business
Compliance and tracking audit, licence-compliant templates, high-intent search or SEO and closed-business reporting. Media is separate.
- Licence-disclosure templates
- Privacy-safe forms
- Closed-business report
- Most popular
Growth program
$10,000–$20,000/mo
Multi-channel · multi-office
Search, SEO, paid social, nurture, reviews and multilingual campaigns run as one plan, reviewed with your compliance team.
- Long-cycle nurture
- Reviews programme
- Multilingual campaigns
Pay-on-results
Base + share
Qualifying firms
A lower base plus a performance fee on closed business above an agreed baseline, structured to meet the compensation rules in your line of business.
- Baseline agreed up front
- Paid on closed business
- Compliance-reviewed terms
Financial services marketing questions
What does a financial services marketing agency in California do?
Do California mortgage ads need an NMLS number?
Do California insurance agents need their licence number on ads?
Can financial advisers use testimonials in California?
How has the home-insurance crisis affected financial marketing?
How do you protect financial data in lead forms?
Which California financial markets do you work in?
How much does financial services marketing cost?
Do you guarantee leads or returns?
More from the San Francisco team
California digital marketing hub
All nine California verticals, the state rulebook and the metros we plan for.ExploreMortgage & lending marketing
Purchase and refinance demand with NMLS disclosures built in.ExploreReal estate marketing in California
A sibling vertical: the agents who refer much of your lending business.ExploreIT & software marketing in California
A sibling vertical, including fintech selling to businesses.ExploreNDAX case study
Regulated fintech acquisition: 4x app users.ExploreSEO agency
The SEO behind high-intent financial content.Explore
Sources and statutes
Every figure and regulation cited on this page.
Facts and thresholds last checked 19 November 2026.
- California Business & Professions Code §10235.5 — NMLS unique identifier in advertisingMortgage loan originators must display their NMLS unique identifier on all advertisements soliciting borrowers.
- California Insurance Code §1725.5 — license number on business cards, quotes and print adsLicensees must print their California license number on business cards, written price quotations and print ads; since 2023 also on email (SB 1242).
- Kitces — The SEC Marketing Rule: testimonials, endorsements and third-party ratingsSEC-registered advisers may use testimonials and endorsements with required disclosures (compliance from 4 November 2022); state-registered advisers follow state rules.
- Insurance Journal — California FAIR Plan policy growth slows (September 2026)Reported at about 696,500 FAIR Plan policies in force in June 2026, with quarterly additions falling for five quarters.
- California Department of Insurance — Natural catastrophe and insurance overview, August 2026 legislative briefTwelve insurance groups have filed under the Sustainable Insurance Strategy; catastrophe models and reinsurance costs now allowed in rate filings.
- California Privacy Protection Agency — 2025 CCPA monetary threshold adjustmentsAnnual gross revenue threshold for a covered 'business': $26,625,000 (Civil Code §1798.140(d)(1)(A)).
Get a compliance and pipeline audit
30 minutes with a senior strategist. Bring your lead sources and closed business if you have them.
What happens next
- 1Pick a time for a 30-minute call.
- 2We review disclosures, forms and sources.
- 3Get a plan measured on closed business.
Prefer email? tarun@conversion.is