Mortgage & lending
Mortgage marketing, for every kind of California borrower
Purchase and refinance loans for California lenders and brokers, with campaigns by loan type and NMLS IDs on every ad.
Trusted by 50+ D2C brands · Google, Meta & Shopify partners
One state, five different mortgage markets
San Francisco, CA
Lenders statewide
NMLS on every ad
B&P Code §10235.5
Funded loans
Not leads
A California buyer looking at an $899,720 median home, or $1.3 million in the Bay Area, is often shopping for a jumbo loan, a first-time-buyer programme or a VA loan, not just 'a mortgage'. Each is a different search, a different borrower and a different compliance check. Treat them as one campaign and you pay Bay Area click prices to reach borrowers who need an FHA loan in Fresno.
Mortgage demand also follows rates. When rates fall, refinance searches surge and every lender bids at once. When they rise, purchase business depends on realtor relationships and pre-approvals made months before an offer. Lenders who only advertise when rates are good end up with no pipeline when they're not.
We work with lenders and brokers as part of financial services marketing in California, and statewide coverage from San Francisco. Every ad carries the originator's NMLS identifier, and rate and payment claims follow federal trigger-term rules. We report on applications and funded loans.
Three reasons lender pipelines dry up
None of these is solved by buying more shared leads.
Rate-driven demand comes and goes
Refinance demand jumps when rates fall and disappears when they rise. Lenders who switch marketing on and off with rates have no brand, no list and no realtor relationships when the cycle turns. A steady purchase engine, plus a ready list of past borrowers to contact when rates drop, smooths the pipeline.
One state, very different loans
Bay Area and coastal buyers need jumbo financing; the Inland Empire and Central Valley are full of first-time FHA and down-payment-assistance borrowers; San Diego has many VA borrowers. Each product needs its own pages, keywords and nurture. One generic 'California mortgage' campaign serves none of them well.
Ad copy can trigger disclosure rules
Every ad soliciting borrowers needs the originator's NMLS identifier under B&P Code §10235.5. Mentioning a rate, payment or down payment triggers federal Regulation Z disclosure requirements, including the APR. 'Low rates' banners and payment examples are where most mortgage ads go wrong.
Six pieces of work, purchase to refinance
Purchase search by loan type
Campaigns and pages for jumbo, FHA, VA, first-time-buyer and down-payment-assistance searches, each with its own landing page and disclosures.
Realtor-partner programmes
Co-marketing, open-house support and referral tracking with agents, within RESPA limits on referral payments. Most purchase loans start with an agent recommendation.
Pre-approval funnels
Short pre-approval flows that collect only what's needed to start, then hand off to your secure application system.
Refinance readiness
Past-borrower lists, rate-watch sign-ups and ready-to-launch refinance campaigns, so you move first when rates fall.
Trigger-term and NMLS compliance
Every ad and page reviewed for NMLS IDs and Regulation Z trigger terms before launch, with your compliance team.
Funded-loan reporting
Applications, locks and funded loans by source from your LOS, imported back to ad platforms as offline conversions.
Five lending markets, five loan mixes
What borrowers in each market need, and which loans they're shopping for.
San Francisco Bay Area
A $1,325,000 median (C.A.R., September 2026) makes most purchases jumbo loans. Borrowers often have equity compensation, so income documentation and RSU expertise matter.
Los Angeles & Orange County
Jumbo coastal loans alongside first-time buyers inland. Spanish- and Korean-language lending and fast pre-approvals win offers in competitive neighbourhoods.
San Diego
One of the largest VA-loan markets in the country, with military moves on fixed timelines. VA-specific content and fast closes win.
Inland Empire
A $601,030 median (C.A.R., September 2026) and many first-time buyers priced out of the coast. FHA, down-payment assistance and new-construction lending are the core.
Sacramento & the Central Valley
Bay Area movers buying larger homes, plus first-time buyers in Fresno and Modesto. Relocation content and conventional and FHA loans dominate.
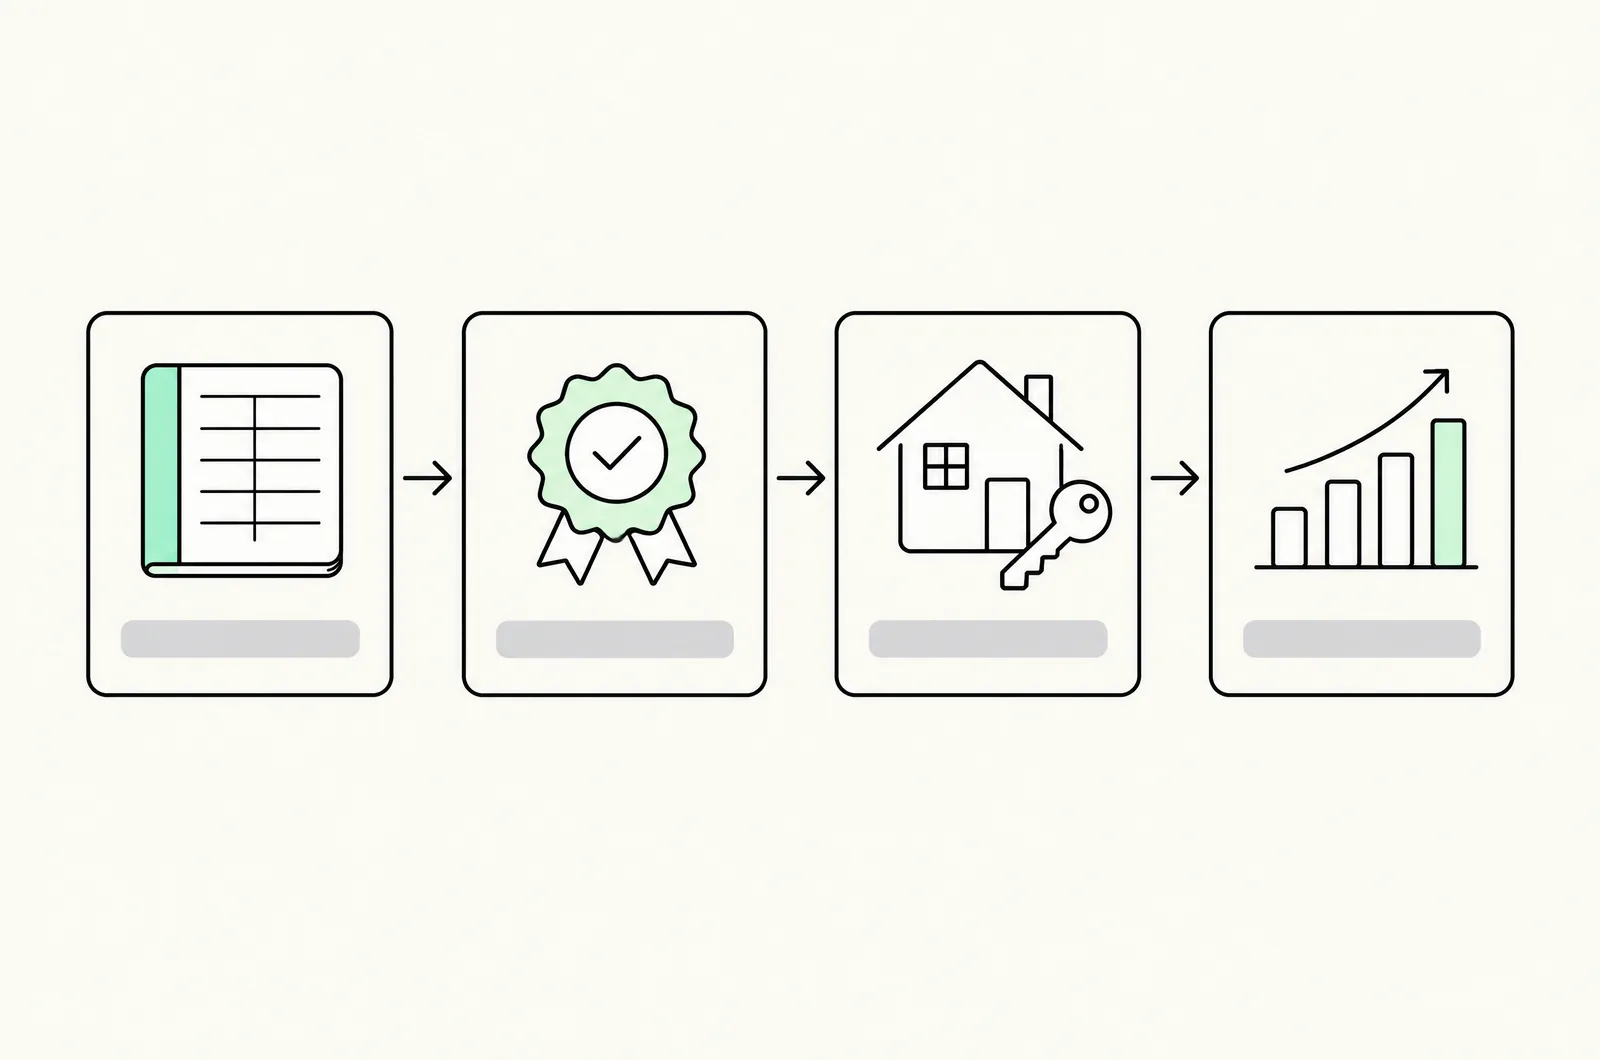
From pipeline audit to funded loans
- Step 01
Pipeline and product audit
Applications, locks and funded loans by source, loan type and region for the last 12 months.
- Step 02
Compliance templates
NMLS IDs and Regulation Z trigger-term rules built into ad and page templates, approved by your compliance team.
- Step 03
Purchase engine and refi readiness
Loan-type search, realtor partnerships and pre-approval funnels, plus a refinance list ready for the next rate drop.
- Step 04
Report funded loans
Monthly applications, locks and funded loans by source and product.
A mortgage specialist vs a lead vendor vs an in-house marketer
In-house costs are directional and depend on seniority and metro.
NMLS ID and trigger-term review on every ad
- Lead vendor
- Often missed
- In-house California hire
- Depends
- Conversion (San Francisco)
- Yes
Campaigns by loan type and region
- Lead vendor
- One mortgage campaign
- In-house California hire
- Limited time
- Conversion (San Francisco)
- Yes
Realtor-partner programme
- Lead vendor
- No
- In-house California hire
- Loan officers' own
- Conversion (San Francisco)
- Yes
Refinance list ready for rate drops
- Lead vendor
- Starts from zero
- In-house California hire
- Sometimes
- Conversion (San Francisco)
- Yes
Reports funded loans by source
- Lead vendor
- Leads
- In-house California hire
- LOS reports
- Conversion (San Francisco)
- Yes
Typical monthly cost
- Lead vendor
- $2,000–$8,000 lead package
- In-house California hire
- $9,000+ per marketer (directional)
- Conversion (San Francisco)
- From $4,500 fee
Search structure, stated plainly
- Search restructure · national
388%
Conversions in 90 days
NP Digital: intent tiers in an expensive auction
NP Digital isn't a lender or a California client, and we have no published mortgage result. What carries over is how the search account was rebuilt by intent with weekly negatives, which lifted conversions 388% and cut CPA 70%. Splitting mortgage search by loan type and region uses the same method.
What mortgage marketing costs in California
USD, excluding media. Performance terms comply with originator compensation and RESPA rules.
Branch foundation
From $4,500/mo
One branch or team
Compliance templates, loan-type search for one region, pre-approval funnel and funded-loan reporting. Media is separate.
- NMLS and trigger-term templates
- Loan-type search
- Funded-loan report
- Most popular
Lender program
$9,000–$18,000/mo
Multi-branch · statewide
Everything in the foundation, plus realtor-partner programmes, refinance readiness, multilingual campaigns and statewide reporting.
- Realtor partnerships
- Refi readiness list
- Multilingual campaigns
Pay-on-results
Base + performance
Qualifying lenders
A lower base plus a performance fee tied to marketing outcomes, structured to comply with loan-originator compensation and RESPA rules.
- Baseline agreed up front
- Compliance-reviewed structure
- Same reporting
Mortgage marketing questions
What must appear on a California mortgage ad?
How do mortgage lenders get purchase business in California?
Can lenders pay realtors for referrals?
How should lenders prepare for refinance waves?
Which California lending markets do you work in?
How much does mortgage marketing cost?
Do you buy mortgage leads for lenders?
How do you track funded loans from marketing?
Related California pages
Financial services marketing in California
The parent practice for lenders, advisers and insurance agencies.ExploreWealth management marketing
A sibling: advisers and RIAs under the SEC Marketing Rule.ExploreInsurance brokerage marketing
A sibling: agencies working through the home-insurance crisis.ExploreReal estate marketing in California
The agents who refer most purchase loans.Explore
Sources and statutes
Every figure and regulation cited on this page.
Facts and thresholds last checked 19 November 2026.
- California Business & Professions Code §10235.5 — NMLS unique identifier in advertisingMortgage loan originators must display their NMLS unique identifier on all advertisements soliciting borrowers.
- California DFPI — Mortgage loan originators
- California Association of REALTORS® — September 2026 home sales and price report (via National Mortgage Professional)Statewide median $899,720; Bay Area $1,325,000; Inland Empire $601,030.
Build a pipeline that survives rate cycles
30 minutes with a senior strategist. Bring applications and funded loans by source if you have them.
What happens next
- 1Pick a time for a 30-minute call.
- 2We review loan mix, sources and ad compliance.
- 3Get a purchase and refi plan.
Prefer email? tarun@conversion.is